Disclosure: We may earn a commission when you buy through links on this page, at no extra cost to you. We buy nothing, sell nothing and accept no payment for coverage — commissions never decide what we recommend. How we make money.
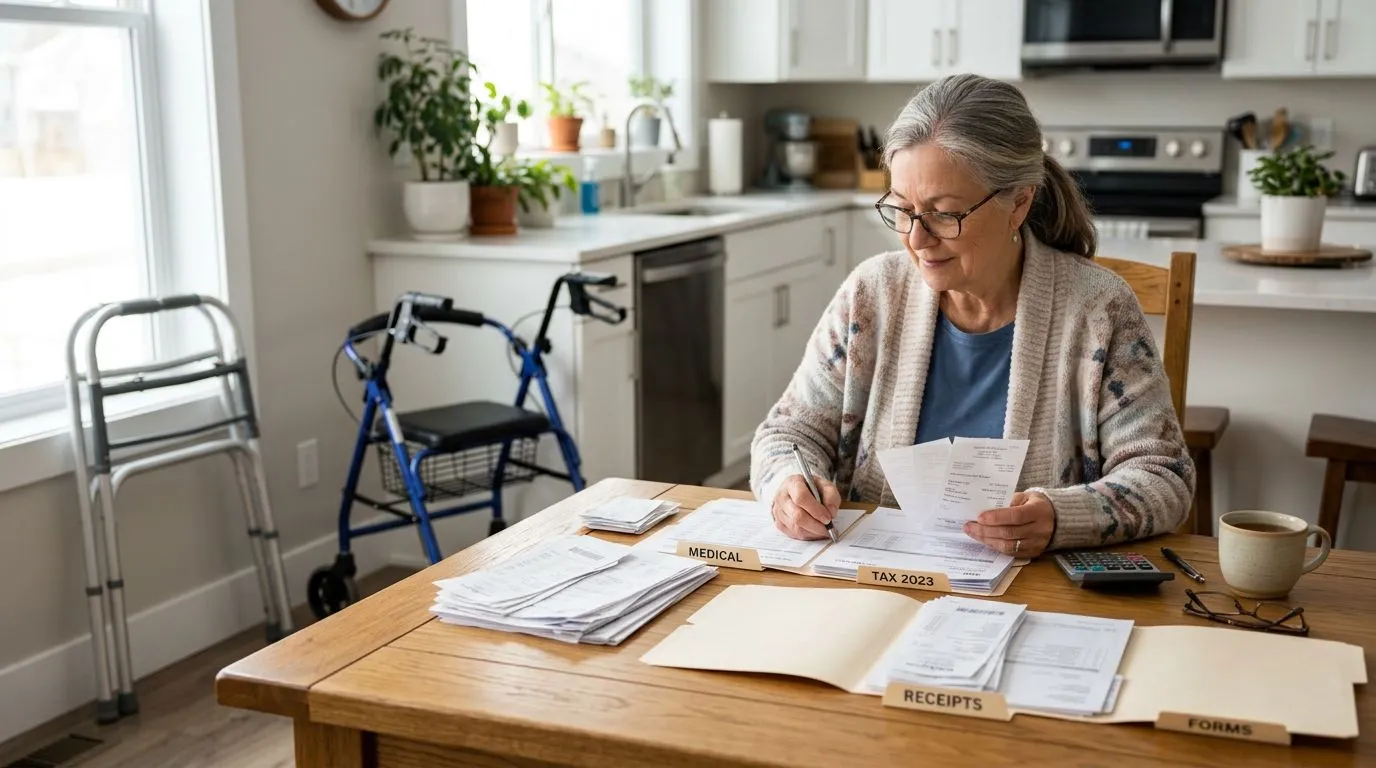
Yes, a walker or rollator may qualify as a medical expense on U.S. taxes if it is used primarily to treat, manage, or alleviate a medical condition or disability. For most taxpayers, the cost helps on a federal return only if you itemize deductions and your total qualified medical expenses exceed 7.5% of your adjusted gross income. Keep the receipt, note the medical reason, and ask a tax professional if the purchase is expensive, reimbursed, or tied to a complicated return.
This article is for U.S. buyers who paid out of pocket for a standard walker, folding walker, two-wheel walker, no-wheel walker frame, or a rollator with wheels, hand brakes, and a seat. It explains the general tax rules in practical terms, but it is not personal tax advice.
The 7.5% AGI rule: why a walker or rollator may not reduce every tax bill
The IRS allows a deduction for qualified medical expenses that are not reimbursed, but there is an important limit. On a federal income tax return, you generally deduct only the portion of unreimbursed medical expenses that exceeds 7.5% of your adjusted gross income, often called AGI. In other words, the walker or rollator may be eligible and still not change your tax due.
Here is a simple example. If your AGI is $50,000, 7.5% is $3,750. If your total unreimbursed qualified medical expenses for the year are $4,200, only $450 is potentially deductible on Schedule A. A walker, rollator, doctor visits, prescriptions, therapy, certain dental costs, and other eligible expenses may all count toward the total, but only the amount above the threshold matters.
You also need to itemize deductions instead of taking the standard deduction. Many taxpayers use the standard deduction because it is larger than their total itemized deductions. In that case, even an eligible walker or rollator purchase may not create a separate tax benefit on the federal return.
That may sound discouraging, but do not throw away your paperwork. Medical expenses can add up during a year with surgery, a fall, joint replacement, stroke recovery, neurological changes, or a new mobility diagnosis. A $75 folding walker or a higher-cost upright rollator may be one part of a larger deduction picture.
Walkers and rollators: 2 related mobility aids, different tax documentation needs
For tax purposes, the main question is not whether the device is called a walker or a rollator. The question is whether it was bought primarily for medical care. Still, knowing the product type helps you describe the purchase clearly when organizing records or discussing it with a tax preparer.
| Mobility aid type | Common features | Typical medical-use reason |
|---|---|---|
| Standard walker or no-wheel frame | 4 legs, lifted with each step, often height adjustable | Extra stability after injury, surgery, weakness, or balance problems |
| Folding walker | Frame folds for storage or car travel; may have no wheels or front wheels | Home and community support when standing or walking is unsafe without assistance |
| Two-wheel walker | 2 front wheels and 2 rear tips or glides | Support for someone who needs stability but cannot safely lift a full frame each step |
| 3-wheel rollator | 3 wheels, hand brakes, compact turning radius, usually no full seat | Light support for indoor or tight-space walking when brakes are appropriate |
| 4-wheel rollator | 4 wheels, hand brakes, seat, backrest, and storage pouch or basket | Walking support plus a place to rest during longer outings |
| Upright or stand-up rollator | Forearm supports or higher handles, 4 wheels, brakes, larger frame | Support for users who need a more upright posture while walking |
| Bariatric rollator or heavy-duty walker | Wider frame and higher weight capacity, often 300 to 500+ lb depending on design | Mobility support for users who need a stronger frame and larger seating area |
A standard walker is usually simpler: four legs, no seat, and a frame that may or may not fold. It is often chosen when maximum stability matters more than speed. A rollator is a wheeled walker with hand brakes, and most 4-wheel versions include a built-in seat. It can make continuous walking easier, but it requires enough hand strength, reaction time, and judgment to control the brakes safely.
In your records, avoid vague labels like household item if the receipt is unclear. A short note such as folding medical walker for post-surgery mobility or 4-wheel rollator with seat for balance impairment can help you remember why the purchase was medical in nature.
3 cost-recovery paths to check before tax time
When people ask about claiming a walker or rollator, they often mean one of three different cost-recovery routes: a tax deduction, reimbursement through a health account, or insurance coverage. These are not the same, and confusing them can cause problems.
| Path | How it may help | Key caution |
|---|---|---|
| Federal medical expense deduction | May reduce taxable income if you itemize and exceed 7.5% of AGI | Only unreimbursed qualified costs count |
| HSA, FSA, or HRA reimbursement | May allow payment with tax-advantaged dollars | Plan rules vary, and documentation may be required |
| Insurance, Medicare, or other coverage | May pay part or all of the cost if coverage requirements are met | You cannot deduct the portion that was reimbursed |
For the federal medical expense deduction, you usually report qualified expenses on Schedule A along with other itemized deductions. You do not submit every receipt with the return, but you should keep records in case you need to support the deduction later.
With an HSA or FSA, the issue is usually whether the walker or rollator is an eligible medical expense under the account rules. Mobility aids used to assist a medical condition commonly fit the medical-care category, but the administrator may ask for a receipt, item description, or letter of medical necessity. Some cards work at medical supply stores, while online or general retail purchases may require you to submit documentation after the purchase.
Insurance is separate. Medicare Part B, Medicaid programs, Veterans benefits, workers compensation, or private insurance may have their own rules for durable medical equipment. They may require a prescription, medical documentation, use of an approved supplier, or prior authorization. If insurance later reimburses you for a rollator you already deducted or paid through a health account, you may need to adjust your tax reporting. That is a good time to ask a professional.
Keep 5 records for a walker or rollator medical expense
A good record file does not need to be complicated. You are trying to show what you bought, when you bought it, what you paid, and why it was connected to medical care. Keep records for at least 3 years after filing, and longer if your tax professional recommends it for your situation.
- Receipt or invoice: Keep the full purchase record showing the date, seller, item description, amount paid, shipping, and sales tax if applicable.
- Proof of payment: Save the credit card statement, canceled check, HSA payment record, or bank transaction that matches the receipt.
- Medical reason: Keep a prescription, discharge instruction, physical therapy note, physician message, or your own dated note explaining the condition or mobility limitation.
- Reimbursement records: Save insurance explanations of benefits, denial letters, HSA or FSA reimbursements, and any amount repaid to you.
- Related expense notes: Record accessories or repairs separately, such as replacement walker tips, wheels, brake adjustments, or a storage pouch, and document why they were needed.
A prescription is helpful, but it is not the only possible documentation for every tax situation. The stronger issue is medical necessity: the device should be primarily for diagnosis, cure, mitigation, treatment, or prevention of disease, or to affect a body function affected by illness or disability. A walker purchased after a hip fracture is easier to support than a device bought only for general fitness walking.
If you buy a rollator with a seat, the seat does not automatically make it nonmedical. Many users need a place to rest because of limited endurance, pain, shortness of breath, or balance concerns. The medical purpose should be clear in your notes or healthcare paperwork.
How to choose and measure: 6 details that affect both safety and receipts
Buying the right device matters for safety first, but it also affects your records. A receipt that says walker, rollator, replacement tips, or brake service is easier to classify than a vague marketplace description. Before buying, measure the user and the spaces where the device will be used.
For most walkers and rollators, handle height should let the user stand upright with shoulders relaxed and elbows slightly bent, often around 15 to 30 degrees. A common measuring method is to stand in regular shoes with arms hanging naturally, then measure from the floor to the crease of the wrist. Many adult walkers adjust roughly within the low-30-inch to high-30-inch range, but exact ranges vary by frame type.
Check weight capacity before purchase. Standard adult walkers and rollators often support around 250 to 300 lb, while heavy-duty or bariatric versions may support 350, 400, 500 lb, or more depending on the frame. Never assume a wider seat means a higher capacity; verify the stated limit.
Width matters too. Interior bathroom doors in older homes may be around 24 inches wide, while many standard interior doors are about 28 to 32 inches. A narrow standard walker may fit where a wider 4-wheel rollator or bariatric rollator does not. If the device is for indoor use, measure the narrowest door, hallway turn, and bedside space before ordering.
| Feature | Walker considerations | Rollator considerations |
|---|---|---|
| Stability | Standard and no-wheel walkers are often best when maximum support is needed | Rollators move continuously and may feel less stable for users who lean heavily |
| Brakes | Usually no hand brakes on standard walkers | Hand brakes must be reachable, easy to squeeze, and lock securely |
| Seat | Usually no built-in seat | 4-wheel and many upright rollators include a seat for rest breaks |
| Transport | Folding walkers are often lightweight and car-friendly | Rollators fold too, but may be heavier and bulkier |
| Outdoor use | Small walker wheels or rubber tips can be difficult on uneven ground | Larger wheels may handle sidewalks better, but brakes and control are critical |
Ask a clinician, physical therapist, or occupational therapist if you are unsure whether a walker or rollator is appropriate. A rollator can be the wrong choice for someone who needs to put substantial weight through the frame, because it can roll away if used incorrectly. A standard walker can also be the wrong choice for someone who cannot lift and place it safely with each step.
Who each device is best for: 4 common buyer situations
There is no single best mobility aid for every person. The right choice depends on balance, strength, endurance, home layout, transportation needs, and whether the user can safely manage wheels and brakes.
After surgery or a short-term injury: A standard folding walker or two-wheel walker is often used during recovery from hip, knee, ankle, or leg problems. The time frame may be a few weeks or several months, depending on the medical plan. Keep discharge papers or therapy notes if they mention a walker.
For significant balance problems: A no-wheel or two-wheel walker may provide more controlled support than a rollator. The slower pace is not a drawback if the main goal is preventing unsafe movement. Rubber tips, rear glides, and correct height adjustment should be checked often.
For longer distances with rest breaks: A 4-wheel rollator with a seat may suit someone who can walk but needs to sit after 100 or 200 feet, such as during shopping, appointments, or community outings. The user must be able to lock the brakes before sitting and should not be pushed while seated unless the device is specifically designed and labeled for that use.
For posture or larger body size needs: An upright rollator may help some users maintain a more forward-facing walking position, while a bariatric walker or bariatric rollator may provide the required frame width and capacity. These devices can be heavier, sometimes 20 lb or more, so lifting them into a vehicle should be part of the decision.
From a tax-record standpoint, any of these may qualify if the medical purpose is real and documented. A luxury preference alone is weaker. A medically necessary feature, such as a higher weight capacity, braking system, seat for endurance limits, or specific frame style recommended by a clinician, is easier to explain.
When 1 purchase becomes partly deductible, reimbursed, or not deductible
The cleanest situation is simple: you buy a medically necessary walker for $90, receive no reimbursement, itemize deductions, and your total medical expenses exceed the 7.5% AGI floor. Real life is often messier.
If insurance reimburses half the cost of a $300 rollator, only the unreimbursed $150 may be considered for a medical expense deduction. If you pay with HSA or FSA funds, you generally should not also deduct that same amount on Schedule A, because you already received a tax advantage. If a family member gives you money as a gift and you buy the device yourself, ask a tax professional how to keep the paperwork straight.
Accessories can be eligible when they are needed for the medical use of the device. Examples may include replacement rubber tips, walker wheels, brake cables, a medically needed tray, or repair parts. General convenience add-ons are more fact-specific. A cup holder or decorative bag may be harder to justify unless it is connected to a medical need, such as safely carrying prescribed medication or necessary supplies.
Shipping and sales tax paid as part of the medical purchase are often tracked with the total cost. Delivery or assembly may be worth documenting if the user cannot safely transport or set up the device. Installation of home modifications, such as ramps or grab bars, follows different rules and may need separate advice.
Ask a tax professional in these 6 situations
Most straightforward walker purchases can be organized with a receipt and basic medical documentation. Professional advice is still worthwhile when the dollar amount is meaningful or the facts are not simple. Tax rules can change, and state rules may differ from federal rules.
- Your total medical expenses are near the 7.5% AGI threshold, and you are unsure whether itemizing is better than taking the standard deduction.
- You used an HSA, FSA, HRA, insurance payment, Medicare, Medicaid, Veterans benefits, or a charitable grant for part of the cost.
- The walker or rollator was purchased for a dependent, parent, spouse, or someone who does not live with you full time.
- You bought a higher-cost upright or bariatric rollator and want to document medical necessity carefully.
- You were reimbursed in a later tax year for an expense you previously deducted.
- You are also claiming related home changes, transportation, long-term care costs, or caregiver expenses.
A tax preparer cannot turn a personal purchase into a medical expense, but they can help you avoid missing legitimate deductions and avoid double-counting reimbursed amounts. Bring the receipt, proof of payment, insurance paperwork, and any medical note that explains why the walker or rollator was needed.
A practical 10-minute checklist before you file
Before tax time, spend 10 minutes putting the mobility-aid paperwork in one folder, digital or paper. Label it by tax year and include the device type, such as two-wheel folding walker or 4-wheel rollator with seat. A few small steps now can prevent confusion months later.
- Confirm the purchase date falls in the tax year you are reviewing.
- Separate unreimbursed amounts from anything paid back by insurance or a health plan.
- Add the cost to your full list of medical expenses for the year, not just mobility equipment.
- Check whether you are itemizing deductions or taking the standard deduction.
- Save medical documentation that connects the device to a condition, injury, surgery, disability, or mobility limitation.
- Ask a tax professional if the answer affects a large refund, a prior-year return, or a dependent claim.
For many U.S. buyers, the most realistic answer is this: a walker or rollator can be a qualified medical expense, but it produces a federal deduction only when the broader tax rules line up. Buy the safest device for the medical need first, keep clear records, and treat any tax recovery as a helpful possibility rather than a guarantee.
FAQ
Frequently asked questions
Is a walker tax deductible as a medical expense? +
A walker may be deductible if it is primarily used for medical care, such as mobility support after surgery, injury, illness, or disability. On a federal return, it generally helps only if you itemize deductions and your unreimbursed qualified medical expenses exceed 7.5% of your adjusted gross income.
Is a rollator with a seat treated differently from a standard walker for taxes? +
Usually the tax question is the same: was it bought primarily for medical care? A rollator with wheels, brakes, and a seat may qualify when it is needed for a medical mobility limitation, but you should keep documentation showing the medical reason.
Do I need a prescription to claim a walker or rollator? +
A prescription or clinician note is strong documentation, especially for insurance or health account reimbursement. For tax deduction records, keep proof that the device was medically necessary, such as discharge instructions, therapy notes, a doctor message, or other medical paperwork.
Can I deduct a walker if Medicare or insurance reimbursed me? +
You generally cannot deduct the portion that was reimbursed. If you paid $200 and later received $120 back from insurance, only the unreimbursed $80 may be considered as a medical expense, assuming the other deduction rules are met.
Can I use HSA or FSA funds for a walker or rollator? +
Many mobility aids used for a medical condition may be eligible for HSA or FSA reimbursement, but plan administrators can require receipts or a letter of medical necessity. Check your plan rules before buying, especially if purchasing from a general retailer.
Should I ask a tax professional before claiming mobility equipment? +
Yes, if the cost is high, you received any reimbursement, you bought it for a dependent or parent, or your total medical expenses are close to the 7.5% AGI threshold. A tax professional can also help prevent double-counting HSA, FSA, or insurance-paid amounts.
Keep reading
Related guides
Walker and Rollator Payment Options: HSA, FSA, Financing, and Tax Deduction Basics
12 min read
Renting vs Buying a Walker or Rollator Through Insurance: What U.S. Seniors Should Know
14 min read
Does Medicare Cover Walkers and Rollators? Costs, Requirements, and What to Ask
12 min read